How insurance agency franchises work
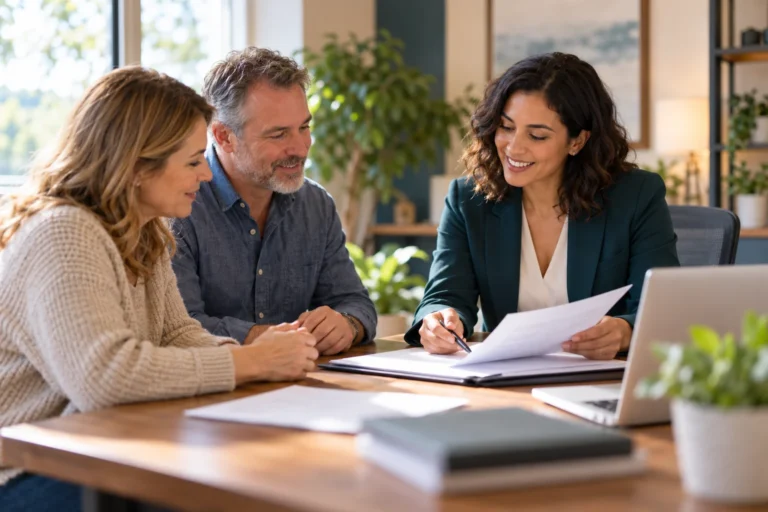
Insurance agency franchises sell personal lines such as home, auto and renters coverage, and often commercial, life and health products, through appointments with several insurance carriers. Customers include families, homeowners, drivers and small businesses that want help comparing options rather than buying from a single company. Many agencies operate from a small office, though some models allow a home base.
Agencies earn commissions from carriers on new policies and on renewals. Because renewal commissions continue as long as clients keep their policies, an agency's value grows with its book of business, and client retention becomes the central performance measure. Revenue in the first years can be lean while the book builds. Licensed staff, quoting technology and carrier access through the franchisor are the main operating ingredients. Cross-selling additional policies to existing households and businesses is a common way agencies deepen each relationship over time.
Why buyers consider insurance agency franchises
- A book that compounds Renewal commissions can stack year over year as long as clients stay with the agency.
- Carrier access A franchise can provide appointments with multiple carriers that a new independent agent might struggle to obtain.
- Essential, recurring need Households and businesses keep buying coverage in most economic conditions.
What it takes to invest
Insurance agency franchises are typically lower in cost than most storefront concepts, often from roughly $30,000 to $120,000 all in, depending on office space, licensing, technology fees and initial staffing. Because commissions build slowly, plan working capital to cover a ramp period before renewals carry the overhead. Item 7 of the Franchise Disclosure Document details the estimated initial investment.
The owner's role
Owners typically start as producers, quoting and selling policies while learning carrier products. As the agency grows, the role shifts toward hiring and coaching licensed agents, managing service staff and marketing to protect retention. You will need a license in each line you sell, and so will your producers. The schedule is office-based and fairly regular, with steady prospecting required to grow the book.
What to evaluate
- Which carriers you will be appointed with and whether appointments are guaranteed or earned
- Who owns the book of business, especially if you sell or leave the system
- How commission splits between the agency, the franchisor and carriers are structured
- Licensing requirements for you and your staff in each line, which vary by state
- Lead generation support and the cost of purchased leads
Who tends to do well
This suits relationship-oriented buyers who are patient with a revenue ramp and comfortable with licensing exams and compliance. Women and veterans often find the professional, community-based role appealing. If you need meaningful income in the first year, or dislike regulated environments, look closely at the ramp before committing.
Questions buyers ask
Do I need an insurance license to own an insurance franchise?
In most cases the owner or a designated agent must hold the appropriate property and casualty or life and health licenses, and producers must be licensed too. Licensing varies by state, so confirm what applies where you live. Franchisors often provide exam preparation.
How do insurance agency franchises make money?
They earn commissions from carriers on new policies and on renewals. Over time renewals can make up a growing share of revenue if retention is strong. Review Item 19 of the disclosure document for any financial performance information the brand provides.
Who owns the clients in an insurance franchise?
Ownership of the book of business varies by brand and is one of the most important terms to understand. Some agreements give the franchisee ownership, while others restrict it. Have a qualified franchise attorney review the agreement before signing.